

First Digital: Agentic AI to reshape payment infrastructure
Thu, 5th Nov 2026 (Today)
AI agents could transact more value than humans within a year-and-a-half, with businesses urged to prepare their payment infrastructure for the emerging machine-driven economy.
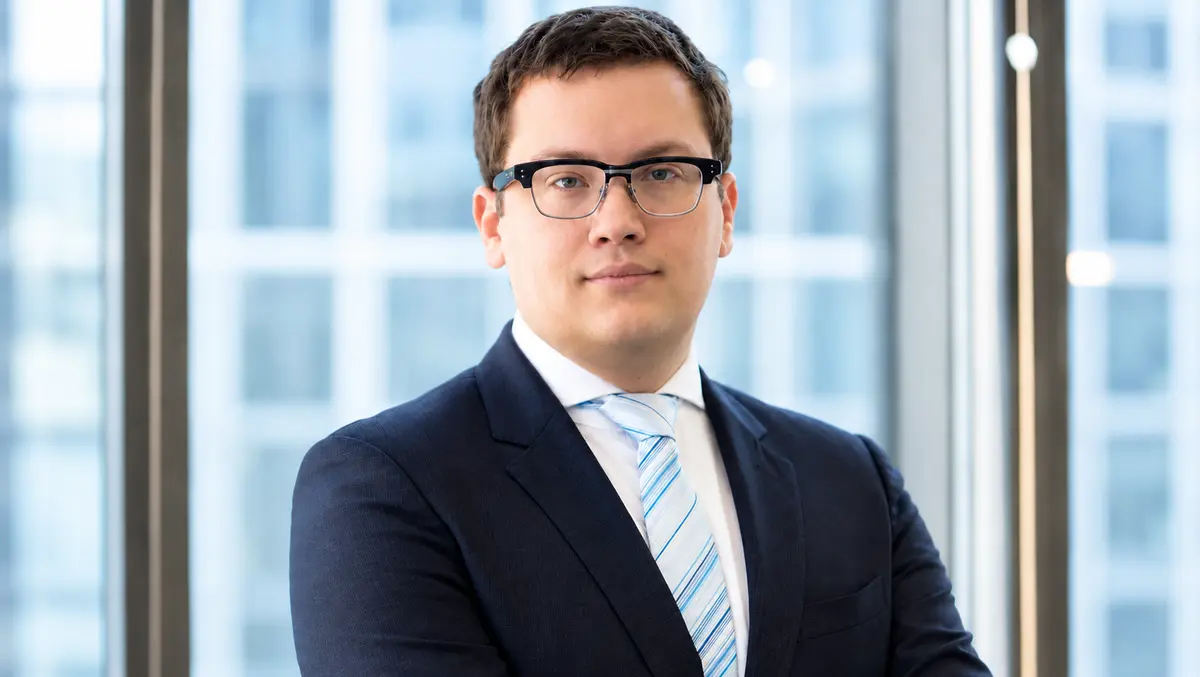
Companies should begin enabling AI agents to make and receive payments, while establishing clear financial policies to prevent autonomous systems from gaining unrestricted access to company funds, according to First Digital COO, Gunnar Jaerv.
Jaerv expects stablecoins and blockchain-based payment infrastructure to play a significant role in the transition, particularly across Asia, where fragmented national payment networks can complicate cross-border transactions.
The convergence of artificial intelligence and digital currencies could fundamentally change how money moves between businesses, consumers and automated systems.
"We believe in the next 12 to 18 months, AI is going to transact more value than humans," Jaerv said.
Businesses need guardrails for AI spending
Organisations should distinguish between accepting payments from AI agents and allowing those agents to spend company money.
Merchants should make it easier for AI systems to purchase products and services through their online stores by integrating compatible payment infrastructure and supporting agent-based transactions, Jaerv explained.
However, giving AI agents unfettered access to corporate bank accounts would not be advisable.
Companies should establish clear policies outlining what an AI agent can purchase, how much it can spend and which transactions it can execute.
Jaerv compared the approach to the controls businesses already place on accountants and other employees responsible for financial transactions.
"Any business can set a policy in the same way, just as you would tell your accountant what they can and cannot pay or what they can and cannot spend," he said.
"You would tell your agent in the same way."
He argued that AI systems can operate within these restrictions, provided businesses establish appropriate rules and controls before deploying them.
The challenge comes in ensuring organisations do not allow automated systems to interact with their finances without clearly defined boundaries.
For businesses that accept payments, however, the immediate priority should be ensuring their infrastructure can accommodate transactions initiated by AI agents.
Supporting cryptocurrency payment mechanisms will become increasingly important, with current AI systems not well-suited to transacting through traditional infrastructure.
Companies that adapt early could gain access to new customers and markets as automated purchasing becomes more common.
Responsibility still lies with humans
The prospect of AI agents executing financial transactions also raises questions about accountability when something goes wrong.
Jaerv argued that organisations must take responsibility for designing and implementing appropriate financial controls, rather than treating AI-related mistakes as a new category of risk.
He compared potential AI payment failures with existing problems involving fraudulent transactions, scams and mistakes made by human employees.
Businesses should approach AI payments with the same emphasis on compliance and risk management that financial institutions apply to conventional transactions, including documenting company-wide policies, identifying potential risks and assigning responsibility for overseeing automated financial processes.
An employee responsible for accounts receivable could establish the rules governing how AI processes incoming payments, ensuring the relevant controls are understood across the organisation.
Jaerv expects more formal standards to emerge as businesses gain more experience with the technology.
AI-specific accounts receivable and accounts payable standards could eventually provide organisations with default policies they can adapt to their own operations.
Today, the market remains in its early stages. Developing these standards will require input from compliance specialists and other industry participants.
Traditional payment systems may struggle to adapt
AI-driven commerce will require a different approach to payment infrastructure, instead of simply adapting existing systems designed around human users.
Traditional card payments, for example, often require customers to complete authentication steps, approve transactions through banking applications or respond to additional security checks.
While these measures help protect consumers and merchants against fraud, Jaerv said they can introduce friction when transactions are initiated by automated systems operating at machine speed.
AI agents require infrastructure capable of transferring value rapidly, communicating directly with other systems and making transaction decisions programmatically.
Stablecoins and other cryptocurrencies could help support this model by enabling digital value transfers through blockchain-based networks.
AI decision-making systems operate within hundreds of milliseconds, creating opportunities for payment processes that are significantly faster than conventional consumer transactions.
A transaction between an agent and a merchant could potentially be completed within five or six seconds, depending on the systems involved.
Merchants could also use AI to assess incoming transactions and identify potential fraud, creating opportunities to automate security checks on both sides of a payment.
Jaerv acknowledged that the transition would introduce new challenges, even as it creates opportunities for faster and more automated commerce.
He expects a parallel payment ecosystem to develop gradually, with fintech startups and younger, more agile companies likely better positioned to build infrastructure suited to AI than established financial institutions with decades of legacy systems.
Asia presents stablecoin opportunities
First Digital has identified Asia as a particularly promising market for blockchain-based payments, based on the fragmentation of its financial infrastructure.
Unlike regions with highly integrated payment networks, Asian economies operate a variety of domestic payment systems that do not always communicate effectively across borders.
International payments across the region still rely heavily on traditional infrastructure, creating opportunities for alternative payment mechanisms.
Governments are also beginning to recognise the potential of stablecoins for international payments.
Jaerv cited Hong Kong's stablecoin legislation and developments in South Korea and Singapore as examples of growing interest in the sector.
Stablecoins are cryptocurrencies designed to maintain a relatively stable value, commonly by referencing a traditional currency such as the US dollar.
Locally denominated stablecoins, possibly issued through partnerships between governments, banks and private companies, could become more prevalent in national economies.
Interoperable blockhain-based payment infrastructure could eventually connect these systems, enabling more efficient cross-border value transfers between different markets.
Crypto, AI industries move closer together
First Digital has historically focused on payment infrastructure and stablecoins, with much of the sector's activity centred on cryptocurrency trading.
Jaerv said the growing capabilities of AI agents are creating new opportunities for the digital asset industry to expand beyond those established use cases.
He also noted that traditional financial institutions already use blockchain technology for tasks such as tokenising shares, suggesting the underlying infrastructure has applications beyond cryptocurrency trading.
The next challenge will be bringing together established digital asset infrastructure and emerging AI technologies to support automated transactions at scale.
Jaerv expects the pace of change to accelerate as AI systems move beyond answering questions and begin carrying out increasingly complex tasks.
"The movement of value and movement of money, that's a whole unexplored area," he said.